Effective Strategies for Building Financial Buffers in the UK
Understanding the Savings Landscape of UK Households
Assessing the stability of income and analysing spending habits are crucial for households across the UK. This examination reveals financial vulnerabilities, particularly in times of economic downturn. Many families experience income variability, making it challenging to sustain consistent savings. By focusing on these aspects, individuals can adopt specific strategies aimed at improving their financial preparedness and resilience in the face of potential crises.
Families should closely evaluate their expenditure and prioritise essential costs. This approach clarifies potential savings opportunities, enabling them to direct more funds towards building financial reserves. Regular reviews of savings ensure that individuals remain informed and can make necessary adjustments, preparing them for unexpected financial hurdles.
What Makes an Emergency Fund Essential for Financial Security?
Establishing a dedicated emergency fund is a fundamental step towards fostering financial security. This fund serves to cover unforeseen expenses, such as vehicle repairs or job losses, which are frequent occurrences in the UK. By committing to save a specific amount on a monthly basis, individuals can gradually build a safety net that assures long-term stability and peace of mind.
An effective emergency fund should typically contain three to six months’ worth of essential living expenses. This buffer is invaluable during periods of financial instability. It is important to keep these funds accessible, yet distinct from daily spending accounts, to reduce the temptation to dip into savings for non-emergency expenditures.
Which Government Support Schemes Can Enhance Financial Stability?
The UK government provides a range of support schemes, such as Universal Credit, Jobseeker’s Allowance, and housing benefits, which offer additional financial protection during challenging times. Exploring these resources allows residents to maximise their entitlements and access essential support when faced with economic difficulties.
Staying informed about changes to government support schemes is vital, as criteria for eligibility and the nature of assistance can evolve. A comprehensive understanding of these resources enables individuals to navigate tough times more effectively, thereby enhancing their financial stability and facilitating informed decisions regarding their finances.
How Can Budgeting Techniques Improve Savings Potential?
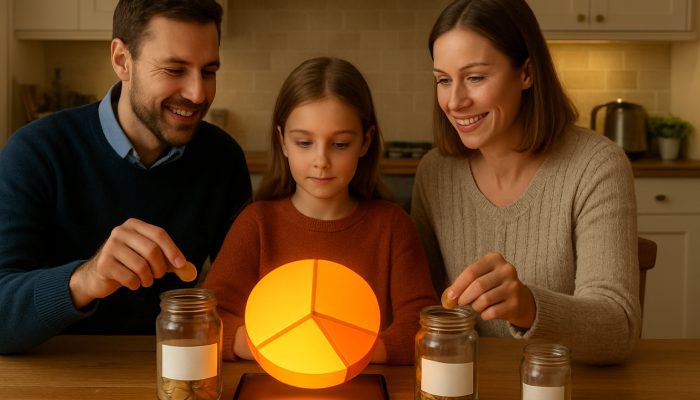
Implementing effective budgeting techniques is essential for families aiming to establish substantial financial reserves. Techniques like the 50/30/20 rule assist individuals in allocating their monthly income towards savings, necessary expenses, and discretionary spending. This method encourages regular contributions to savings, thus improving preparedness for unexpected financial issues.
Consistent review and adjustment of budgets are crucial to ensure they remain aligned with changing financial objectives. By utilising budgeting tools and apps, families can gain insights into their spending patterns, enabling them to identify improvement opportunities and ultimately enhance their economic security amidst fluctuating circumstances.
Why Is Reviewing Insurance Options Critical for Financial Safeguarding?
Reviewing various insurance options is an important step in protecting accumulated reserves against potential losses. Residents in the UK should consider a range of policies, including health, home, and income protection insurance, to secure comprehensive coverage. These measures can significantly mitigate the financial impact of accidents, illnesses, or property damage.
Investing in robust insurance policies not only shields personal assets but also fosters peace of mind. By understanding the different insurance products available, individuals can make informed choices that align with their financial goals, ensuring long-term stability and security.
Insights from Experts on Creating Financial Buffers for Future Resilience
Showcasing Successful Community Initiatives in the UK
Community initiatives throughout the UK have effectively countered the impacts of recent economic events through collaborative savings groups. For instance, credit unions in Wales and Scotland have provided essential financial services, allowing members to save collectively and access low-interest loans during challenging periods.
These community-driven efforts have strengthened resilience among participants, demonstrating the power of collaboration. By pooling resources and sharing knowledge, individuals can build stronger financial buffers, ensuring they are better prepared for future economic uncertainties.
How Can Policy Revisions Enhance Economic Resilience?
Recent changes to fiscal policies in the UK have created new opportunities for improved support structures. For example, alterations to tax relief for savings and investments can encourage individuals to enhance their financial reserves more effectively. Being aware of these policy changes enables residents to adjust their financial strategies and benefit from new regulations.
By remaining informed about government modifications, individuals can navigate the financial landscape with greater competence. This adaptability is crucial for enhancing personal stability and resilience, particularly in a fast-evolving economic environment.
What Practical Steps Can Facilitate Effective Implementation?
To successfully establish financial buffers, UK residents should adopt practical strategies tailored to their circumstances. Start by creating a comprehensive budget, identifying potential saving areas, and setting specific savings goals. This organised approach allows individuals to consistently allocate funds towards their financial reserves.
Automating savings transfers can simplify this process. By establishing direct debits to a dedicated savings account, individuals prioritise saving each month. This disciplined approach fosters a saving habit and ultimately leads to enhanced financial security.
Why Is Diversifying Investments Essential for Financial Security?
Diversifying investment portfolios plays a critical role in creating robust buffers against unforeseen economic disruptions. Leading financial experts in the UK emphasise the necessity of incorporating various asset types, such as stocks, bonds, and real estate, to reduce risk and enhance overall returns. This strategy not only shields against market fluctuations but also opens avenues for growth.
By distributing investments across multiple sectors, individuals can protect their financial reserves. This diversification equips residents to better endure economic turbulence, ensuring long-term financial stability and security in an unpredictable environment.
How Can Technology Aid in Building Financial Buffers?
Contemporary financial technology applications are reshaping how individuals manage their finances in the UK. These innovative tools allow users to automate regular savings, track spending habits, and set financial goals. By harnessing technology, individuals can strengthen their resilience against potential future economic shocks through disciplined financial management.
Utilising applications that monitor expenses and offer insights into spending behaviours empowers users to make informed decisions. This proactive approach nurtures a culture of saving and responsible financial management, ultimately contributing to more robust financial buffers.
Effective Resource Allocation Management for Stability
Identifying Supply Chain Vulnerabilities and Dependencies
Examining the reliance on imports and domestic production in the UK uncovers areas that require diversification to prevent disruptions during supply shortages. Recent events, such as the COVID-19 pandemic, have underscored the importance of recognising these vulnerabilities, prompting both businesses and households to re-evaluate their resource allocation tactics.
By pinpointing critical weaknesses in supply chains, individuals and organisations can devise contingency plans. This proactive strategy ensures preparedness for potential disruptions, securing financial stability and access to essential goods and services.
What Strategies Promote Sustainable Stockpiling Practices?
Developing effective plans for the storage of essential goods is crucial for British households aiming to maintain access during uncertain times. Focusing on non-perishable items, such as canned goods, dried foods, and toiletries, ensures families are well-prepared to tackle unexpected challenges, ranging from natural disasters to economic downturns.
To stockpiling non-perishables, households should implement a rotation system to manage their supplies effectively. This method minimises waste and ensures that items remain fresh and usable. With strategic planning, families can bolster their resilience and readiness for future disruptions.
How Can Technology Support Effective Resource Monitoring?
Using digital tools available in the UK allows for real-time tracking of resource levels, facilitating proactive adjustments to buffer systems. Numerous applications and platforms enable households to monitor their inventories, ensuring they are aware of available resources and the optimal times to replenish supplies.
By integrating technology into resource management, individuals can make well-informed decisions regarding their needs. This proactive methodology fosters a culture of preparedness, ensuring that families are well-equipped to navigate uncertainties and maintain stability during challenging periods.
Research-Backed Advantages of Establishing Financial Buffers for Future Resilience
Analysing Economic Data from Recent Challenges
Reviewing reports on UK recessions demonstrates how pre-existing buffers significantly alleviated financial strain for numerous households and businesses. Data indicates that families with established emergency funds managed to weather economic downturns more effectively, allowing them to navigate financial storms without resorting to high-interest debt.
These findings highlight the importance of proactive financial planning. By creating buffers, individuals can enhance their resilience and better prepare for future economic challenges, ultimately resulting in greater financial security.
Highlighting Exemplary Practices from UK Industries
Industries such as manufacturing have successfully implemented buffer strategies to overcome past challenges in the UK. For instance, companies that adopted inventory management systems during economic downturns were able to maintain operations and protect jobs, showcasing the effectiveness of strategic resource allocation.
These practical examples underscore the necessity of adopting buffer strategies across various sectors. By learning from successful practices, businesses can develop tailored approaches that bolster their resilience and ensure long-term stability in an ever-shifting market.
Exploring the Impact on Health and Wellbeing
Investigating the correlation between financial security and mental health in the UK reveals the broader benefits of proactive buffer building. Research indicates that individuals with established financial reserves experience lower levels of stress and anxiety, contributing to an overall sense of wellbeing.
By prioritising financial stability, individuals can improve their quality of life. This holistic viewpoint acknowledges that building buffers not only protects against economic shocks but also fosters a healthier, more balanced lifestyle.
What Are the Long-Term Benefits of Building Financial Buffers?
Tracking Financial Progress Over Time
Assessing the effectiveness of financial buffers through annual reviews enables UK residents to refine their strategies in light of changing personal and national circumstances. Regular evaluations help individuals identify improvement areas and adjust their methods, ensuring ongoing relevance and effectiveness.
By establishing long-term financial goals and monitoring progress, individuals can remain accountable and motivated. This ongoing evaluation process promotes a culture of financial responsibility, ultimately leading to sustained stability and resilience in the face of future challenges.
How Can Strategies Adapt to Changing Economic Conditions?
Modifying strategies in response to interest rate fluctuations is vital for maintaining the strength of financial safeguards in the UK. As economic conditions shift, individuals must be ready to adjust their budgets and investment strategies to align with their financial objectives.
By staying informed about economic trends and developments, residents can make informed decisions that enhance their financial resilience. This adaptability is essential for navigating the complexities of a dynamic financial landscape.
What Are the Advantages of Community Support Networks?
– Strengthened relationships among neighbours
– Enhanced resource sharing during crises
– Increased access to local knowledge and skills
– Greater emotional support during challenging times
Collaborative efforts among neighbours in the UK can significantly enhance community resilience. By sharing resources and expertise, individuals create a supportive network that aids everyone in navigating prolonged difficulties more effectively.
How Does Financial Independence Foster Lasting Security?
Reflecting on the sustained financial stability achieved through consistent buffering practices empowers UK residents to attain greater independence and security amid future uncertainties. By prioritising financial planning and building buffers, individuals can navigate economic challenges and personal transitions with confidence.
This proactive approach not only fortifies individual resilience but also nurtures a more stable and secure community. As people embrace financial independence, they cultivate a culture of responsibility and preparedness that benefits all.
Frequently Asked Questions
What is the purpose of building financial buffers?
Building financial buffers prepares individuals for unexpected expenses or economic downturns, offering a safety net that enhances financial stability and security.
How much should I save for an emergency fund?
It is generally advised to save three to six months’ worth of living expenses in an emergency fund to effectively cover unforeseen costs.
What government support schemes are available in the UK?
The UK provides various support schemes, including Universal Credit, Jobseeker’s Allowance, and housing benefits, to assist residents during financial hardships.
What budgeting techniques can enhance savings?
Techniques such as the 50/30/20 rule and zero-based budgeting can help individuals allocate their income efficiently, prioritising savings and essential expenses.
How can I diversify my investment portfolio?
To diversify your portfolio, consider integrating a mix of asset classes such as stocks, bonds, and real estate, which can help mitigate risk and enhance returns.
What role does technology play in financial management?
Technology streamlines financial management through applications that automate savings, track spending, and provide insights, assisting users in building effective financial buffers.
How can I identify supply chain vulnerabilities?
Identifying supply chain vulnerabilities involves analysing dependencies on imports and domestic production, enabling individuals and businesses to formulate diversification strategies.
What are the benefits of stockpiling essential goods?
Stockpiling essential goods ensures access during uncertainties, minimises panic buying, and allows households to maintain stability amid disruptions.
How can I monitor my resource levels effectively?
Utilising digital tools and applications can assist in tracking resource levels in real-time, enabling proactive adjustments to ensure sufficient supplies.
What are the long-term outcomes of building financial buffers?
Long-term outcomes include enhanced financial independence, improved resilience against economic shocks, and a greater sense of security and wellbeing.
Visit our Facebook profile today!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk
The Article Buffers for Absorbing Future Shocks: Essential Tips found first on https://electroquench.com