
The Comprehensive Guide for Renters in the UK: Understanding Debt Consolidation
Evaluating Your Financial Landscape
Before starting the debt consolidation process as a renter in the United Kingdom, it is essential to thoroughly evaluate all your existing debts, including credit card balances and personal loan obligations. Begin by calculating your monthly expenses and comparing them with your income from employment or benefits. This comprehensive assessment will enable you to pinpoint your actual repayment capacity. A solid understanding of your financial situation allows you to make informed decisions about which debts to consolidate.
After evaluating your financial landscape, creating a practical budget is crucial. Be sure to consider essential expenses like rent, utility bills, and groceries. By developing a detailed overview of your finances, you can spot areas where spending can be reduced, allowing you to allocate more funds toward debt repayment. This meticulous evaluation is fundamental for a successful debt consolidation strategy.
Exploring Debt Solutions Specifically for Renters
As a tenant, it is wise to investigate options such as debt management plans and individual voluntary arrangements provided by accredited organisations in the UK. Each solution has its own set of advantages and disadvantages, making it crucial to ensure they comply with your rental agreements. Conducting thorough research is necessary to avoid violating tenancy terms during the consolidation process, as such breaches could jeopardise your housing situation.
Consider alternatives like debt consolidation loans or balance transfer credit cards to alleviate your financial strain. It is important to understand the related terms and conditions, particularly regarding their potential impact on your rental responsibilities. Being well-informed enables you to select the most appropriate solution for your specific financial circumstances.
Obtaining Professional Advice from Regulated Organisations
Engaging with organisations such as <a href=”https://www.debtconsolidationloans.co.uk/stepchange-vs-debt-consolidation-loans-compared/”>StepChange</a> or Citizens Advice can provide invaluable support concerning debt consolidation for renters. These organisations offer free expert guidance that helps you navigate your options while steering clear of unregulated companies that might charge excessive fees. Seeking professional assistance is a vital step in making well-informed financial choices.
For personalised support, these organisations also offer resources and tools to help you manage your debts more effectively. They can assist you in creating a tailored plan that takes into account your rental status and financial commitments. This guidance is essential for avoiding the common pitfalls often encountered in the debt consolidation process.
Expert Insights on Effective Debt Consolidation Strategies for Renters
Insights from Real-World Case Studies in the UK
Insights derived from real-world UK case studies highlight the importance of understanding lender criteria when consolidating debts. For instance, tenants may need to demonstrate their eligibility for balance transfer cards or consolidation loans, as approval often depends on their rental status. Grasping how lenders evaluate applications can significantly impact approval rates and interest charges.
These case studies underscore the necessity of maintaining open communication with creditors. Direct engagement with lenders can lead to more favourable terms, particularly for renters who may encounter unique challenges in securing loans. Learning from the experiences of others can aid in adopting a more effective approach to the debt consolidation endeavour.
What Characteristics Lead to Successful Expert Strategies?
Experts suggest that tailoring consolidation plans to comply with UK housing regulations is crucial to ensure that debt merging adheres to landlord permissions. This strategic alignment is vital to avert eviction notices during periods of financial restructuring. By considering the specifics of rental agreements, you can formulate a sustainable plan that respects both your financial obligations and housing stability.
Successful strategies typically involve regular evaluations and adjustments based on changing circumstances. As your financial situation evolves, it is important to remain flexible and modify your debt consolidation plan accordingly. This ongoing assessment helps maintain a healthy balance between debt repayment and rental responsibilities.
Grasping the Implications of Affordability Checks
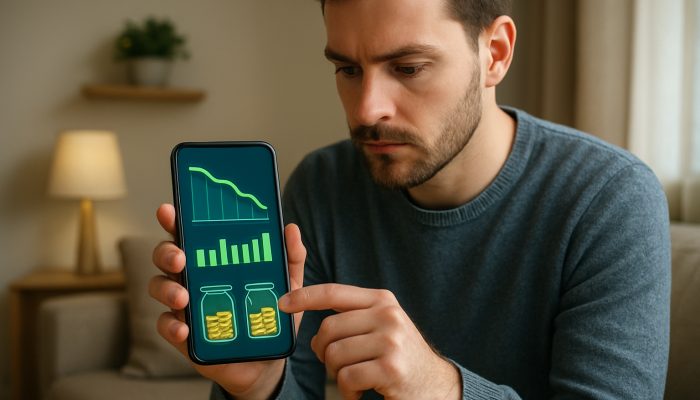
Utilising budgeting tools can provide substantial advantages for UK renters aiming to consolidate debts. These tools assist in ensuring steady rental payments while simultaneously reducing interest obligations. The primary benefits of using budgeting tools include:
- Efficient tracking of income and expenses
- Identifying potential savings
- Setting achievable financial goals
- Monitoring progress toward debt repayment
By employing these tools, renters can establish a clear financial roadmap that supports their debt consolidation efforts. This structured approach not only aids in managing existing debts but also fosters long-term financial health, ensuring that rental obligations are consistently met.
Understanding the Role of Guarantors in Debt Consolidation
UK experts indicate that renters often need guarantors when applying for loans to consolidate debts. This requirement arises from the perceived risk associated with lending to tenants. Choosing suitable guarantors who comprehend the implications for rental agreements and ongoing financial commitments is essential for safeguarding housing security.
Maintaining transparent communication with your guarantor about your financial situation and potential risks is vital. Ensuring they are adequately informed can prevent misunderstandings and strengthen the support network surrounding your debt consolidation efforts. A well-chosen guarantor can offer crucial assistance in navigating the complexities of debt merging.
Evaluating Tax Considerations for Debt Consolidation Strategies
Financial advisors recommend assessing any potential tax reliefs available in the UK for individuals consolidating debts while renting. Understanding these implications is crucial, as strategies that appear beneficial at first could inadvertently impact eligibility for housing benefits or other essential supports necessary for maintaining tenancy stability.
Consulting with tax professionals or financial advisors ensures that your debt consolidation efforts do not lead to unexpected financial consequences. This proactive approach enables you to optimise available resources while protecting your housing situation, ultimately paving the way for a more secure financial future.
What Strategies Can Renters Use to Effectively Consolidate Debts?
Engaging in Direct Negotiations with Creditors
UK tenants often gain by directly contacting lenders to consolidate accounts into a single, manageable payment schedule. This method respects tenancy obligations and helps prevent arrears on vital housing costs. Taking the initiative to negotiate may yield more favourable terms that correspond with your financial capabilities.
Direct negotiation can also cultivate a more personal relationship with creditors. Establishing rapport may lead to increased flexibility in payment arrangements and a greater willingness to accommodate your specific financial circumstances. Open communication is essential for successfully merging debts while fulfilling your rental commitments.
Maximising Opportunities for Balance Transfers
Exploring Zero per cent credit card transfers available in the United Kingdom enables renters to temporarily consolidate unsecured debts, reducing overall costs. This option can be especially advantageous for those looking to merge debts without incurring high interest rates. It is crucial to read the fine print and fully understand any fees associated with balance transfers.
Ensuring compliance with lease agreements throughout this process is essential. Renters should verify that any new financial commitments do not hinder their ability to meet rent payments. By carefully analysing balance transfer options, you can effectively manage your debts while protecting your housing security.
How Do Credit Scores Affect Debt Consolidation Outcomes?
Monitoring your credit file through agencies like Experian reveals how merging debts while renting may gradually enhance your ratings over time. Consistent payments within agreed limits can positively influence your credit score, making it easier to secure future loans or rental agreements. Understanding this connection is vital for renters aiming to improve their financial standing.
Maintaining a strong credit score can unlock access to better interest rates and loan options in the future. As you consolidate debts and make timely payments, you are likely to observe gradual improvements in your creditworthiness. This positive trend can bolster your financial stability and provide more opportunities within the rental market.
Investigating Debt Consolidation Loans Options
Renters in the UK considering consolidation loans from reputable lenders can merge various unsecured debts into a single monthly payment, potentially at a lower interest rate. This arrangement ensures that your financial responsibilities remain aligned with tenancy terms, avoiding negative effects on critical housing payments or credit history.
Choosing a trustworthy lender who understands the specific challenges faced by renters is essential. This careful selection enables you to formulate a debt consolidation plan that simplifies your financial responsibilities while supporting your long-term housing stability. Achieving a successful debt merging strategy relies on this thoughtful approach.
Evidence-Based Benefits of Debt Consolidation for Renters
Providing Practical Steps for Effective Execution
Research from UK financial institutions indicates that structured debt consolidation reduces stress for renters by simplifying payments and freeing up funds for essential household expenses. This method allows individuals to focus on meeting their rental obligations without the burden of multiple debts. Implementing a clear plan can significantly enhance financial wellbeing.
By streamlining debt payments, renters can direct more resources toward savings or unexpected expenses. This financial flexibility is crucial for maintaining stability in rented accommodation. By following actionable steps, individuals can create a more secure financial environment while effectively managing their debts.
Evaluating Long-Term Financial Impacts of Debt Consolidation
Studies show that UK residents who consolidate debts through approved methods often incur lower total interest payments. This strategy frequently results in quicker debt resolution while preserving a positive rental history. Recognising the long-term advantages of debt consolidation can inspire renters to take proactive measures in managing their finances.
A well-executed debt merging strategy can improve overall financial health, facilitating a smoother transition to homeownership in the future if desired. By prioritising sustainable debt repayment, renters can lay a strong foundation for their financial future while enjoying the stability of their rental accommodation.
Learning from Real-World UK Case Studies
Expert analyses illustrate how debt consolidation fosters stable living arrangements in rented properties throughout the United Kingdom, emphasising the importance of aligning repayment plans with variable income patterns. For example, case studies reveal that renters who consolidate debts frequently experience improved cash flow, enabling them to meet both debt obligations and rental payments more easily.
These real-world examples underscore the tangible benefits of debt consolidation, showcasing how it can lead to enhanced financial stability. By drawing lessons from others’ experiences, renters can better navigate their own debt merging journeys and secure a more stable financial future.
Evaluating Improvements in Credit Ratings
UK studies from credit reference agencies suggest that consolidating debts for renters frequently results in improved credit ratings over time. This enhancement can facilitate easier access to future rental properties, reducing the risk of rejection associated with elevated debt levels. Understanding the positive relationship between debt consolidation and credit scores is essential for renters pursuing financial growth.
A higher credit score can unlock more favourable terms on loans and financial products. As renters consolidate debts and commit to timely payments, they can progressively enhance their creditworthiness, making it easier to secure housing options that meet their needs. This upward trajectory can greatly influence long-term financial wellbeing.
Examining the Mental Health Benefits of Debt Consolidation
Research conducted by UK mental health charities highlights that debt consolidation for renters alleviates anxiety and enhances overall wellbeing. Establishing manageable repayment schedules that align with variable earnings can significantly reduce financial stress. This aspect of mental health is often overlooked yet plays a crucial role in overall quality of life.
By simplifying financial obligations, renters can focus more attention on other important areas of life, such as work and personal relationships. This holistic approach to financial health can help cultivate a more balanced and fulfilling lifestyle. Prioritising mental wellbeing alongside financial stability is essential for renters navigating the complexities of debt consolidation.
What Solutions Are Available for Tenants with Multiple Debts?
Investigating Government-Supported Relief Initiatives
Initiatives such as breathing space in the UK provide renters with temporary protection from creditor actions. This provision allows time to organise debt consolidation without the immediate threat of losing housing stability. Understanding these government-supported options can offer critical support for renters facing financial challenges.
These schemes often have specific guidelines and eligibility criteria. It is crucial for tenants to familiarise themselves with these requirements to fully benefit from the relief offered. By leveraging these resources, renters can develop a more sustainable financial plan while protecting their housing situation.
Weighing the Advantages and Disadvantages of Loans versus Plans
Tenants should carefully compare personal loans and debt management plans, ensuring that their chosen methods align with the demands of the UK rental market. Each option presents distinct advantages and potential drawbacks, making careful consideration essential. Understanding how these strategies interact with your rental agreement helps mitigate risks associated with financial conduct clauses.
Seeking guidance from financial professionals can facilitate informed decision-making. By evaluating the benefits and disadvantages of each option, renters can pinpoint the most suitable approach for their unique financial situations. This informed decision-making process is crucial for successfully merging debts while meeting rental obligations.
How Can Professional Mediation Assist Renters?
Mediation services regulated in the UK help create unified repayment agreements that protect renters from aggressive collection tactics. These services focus on achieving sustainable outcomes, enabling tenants to negotiate terms that are manageable and considerate of their financial circumstances. Engaging a mediator can provide essential support in addressing complex debt issues.
Professional mediation encourages improved communication between renters and creditors. This collaborative approach may lead to more favourable repayment arrangements and alleviate the stress associated with debt management. By utilising mediation services, tenants can work towards a more stable financial future while safeguarding their housing security.
Effective Steps for Implementing Debt Consolidation Strategies
Developing a Comprehensive Personal Budget
Creating detailed monthly plans in the UK that allocate funds for consolidated debts alongside rent is essential. This ensures that vital living expenses remain covered. A well-structured budget acts as a foundation for successfully merging debts while maintaining housing stability and fulfilling financial obligations.
Regularly reviewing and adjusting your budget can accommodate changes in income or unexpected expenses. This proactive approach enables renters to stay on top of their financial situations and make necessary modifications as circumstances evolve. By prioritising budgeting, you can establish a sustainable financial plan that supports both debt repayment and rental commitments.
Continuously Monitoring Your Progress
Regular reviews assist UK renters in adapting strategies for merging debts while renting should circumstances change, such as income fluctuations or unforeseen tenancy-related costs. By remaining vigilant and proactive, you can ensure that your debt consolidation plan stays effective and aligned with your financial objectives.
Tracking your progress can also provide motivation and reassurance. Observing improvements in your financial situation can boost confidence and encourage continued commitment to the debt merging process. This ongoing evaluation fosters a sense of control over your finances, contributing to a more stable and secure rental experience.
Avoiding Common Missteps
Avoid high-interest options by engaging exclusively with regulated UK providers that specialise in tenant-friendly consolidation methods. Collaborating with reputable organisations ensures fair treatment and protects you from predatory lending practices that could worsen financial difficulties. This careful selection process is integral to long-term financial health.
Educating yourself about the risks associated with debt consolidation is essential. Understanding potential pitfalls empowers you to make informed choices and safeguard your financial wellbeing. By approaching debt consolidation with caution and awareness, you can navigate the process successfully while maintaining your rental obligations.
Frequently Asked Questions
What does debt consolidation mean for renters?
Debt consolidation for renters entails merging multiple debts into a single payment, thereby simplifying financial management while ensuring that rent obligations are met.
How can I evaluate my financial condition?
Review all outstanding debts, calculate your monthly expenses against your income, and create a detailed budget to identify feasible repayment levels.
What debt solutions exist for tenants?
Options include debt management plans, individual voluntary arrangements, and consolidation loans tailored to meet rental agreements.
How can I seek advice regarding debt consolidation?
Reach out to organisations like StepChange or Citizens Advice for free guidance on merging debts and avoiding unregulated companies.
What is the role of guarantors in debt consolidation?
Guarantors may be needed for loans, and selecting someone who understands the implications for rental agreements and financial obligations is crucial.
Are there tax implications related to debt merging?
Investigate potential tax reliefs available in the UK to ensure that debt consolidation strategies do not impact eligibility for housing benefits.
What is the best way to negotiate with creditors?
Contact lenders directly to discuss merging debts into a manageable payment schedule, potentially securing lower rates in the process.
What balance transfer options are available to renters?
Zero per cent credit card transfers enable renters to temporarily consolidate unsecured debts, reducing overall costs while ensuring compliance with lease agreements.
How do credit scores impact debt consolidation?
Merging debts and making timely payments can improve your credit score, enhancing access to future loans and rental properties.
What actions should I take to implement debt merging strategies?
Create a personal budget, consistently monitor your progress, and avoid high-interest alternatives to ensure successful debt consolidation while upholding rental obligations.
Visit our Facebook page today for more insights!
This Article Was First Found On: https://www.debtconsolidationloans.co.uk
The Article Merging Debts: Practical Guidance for Renters was originally published on https://electroquench.com
